What Happened
Job cost variance is one of those operational signals that often arrives too late. A project looks healthy during the weekly meeting, then a labor overrun, material substitution, delayed change order, or subcontractor issue quietly eats into margin. By the time finance closes the month, the variance is no longer a warning. It is a result. Managers can explain what happened, but they have fewer options to change the outcome.
Many businesses already collect the data needed to spot margin drift earlier. Time entries, purchase orders, approved budgets, change requests, project schedules, field notes, invoice holds, and work-in-progress reports all contain clues. The challenge is that those clues live in different systems and are reviewed at different rhythms. Operations looks at schedule pressure. Finance looks at cost codes. Project managers look at commitments. Executives look at margin. No single person has time to reconcile every signal every day.
AI and automation can turn job cost variance review into a recurring management workflow instead of a periodic accounting surprise. The purpose is not to create a black-box forecast. The purpose is to surface the small mismatches that deserve human attention while there is still time to act. A system can compare budgeted cost, committed cost, actual cost, percent complete, open change orders, and field explanations. It can then route exceptions to the right owner with the evidence needed to make a decision.
This approach is useful for construction firms, professional services teams, field service organizations, agencies, installation businesses, manufacturers, and any company that manages work by project or job. The details vary, but the pattern is consistent. Margin usually drifts before it collapses. The earlier a business sees the drift, the more options it has.
Why It Matters for Businesses
Job cost variance matters because project margin is often won or lost in small decisions. A supervisor approves overtime to protect a deadline. A purchasing team accepts a higher material price to avoid delay. A project manager waits to document a change because the client relationship feels sensitive. Each choice can be reasonable on its own, but together they can turn a profitable job into a weak one.
Traditional reporting often explains variance after the fact. That is useful for accountability, but it is not enough for operational control. Leaders need a way to see which jobs are drifting, why they are drifting, and what action should happen next. Without that workflow, teams may spend review meetings debating whose spreadsheet is current instead of deciding how to protect the outcome.
The business benefits of earlier review are concrete:
- Project managers can request change orders before the work is forgotten.
- Finance can distinguish timing issues from true margin risk.
- Operations can rebalance labor before overtime becomes normal.
- Procurement can flag material substitutions that need client approval.
- Executives can see margin exposure before month-end.
- Teams can learn which variance patterns repeat across jobs.
AI is useful because job cost variance is partly numerical and partly narrative. Numbers show that a cost code is high, but notes often explain why. Field comments, emails, issue logs, and schedule updates may reveal that the overrun came from scope creep, rework, waiting time, training gaps, site access problems, or client-driven changes. Automation can bring those signals together and create a review queue that is easier to trust.
The Practical Automation Opportunity
A practical workflow begins with a variance policy. Define what deserves review. That may include any cost code more than a certain percentage over budget, labor hours rising faster than percent complete, committed costs exceeding remaining budget, unapproved change work, repeated invoice holds, or schedule slippage paired with overtime. The thresholds should be simple at first. A noisy workflow will lose credibility quickly.
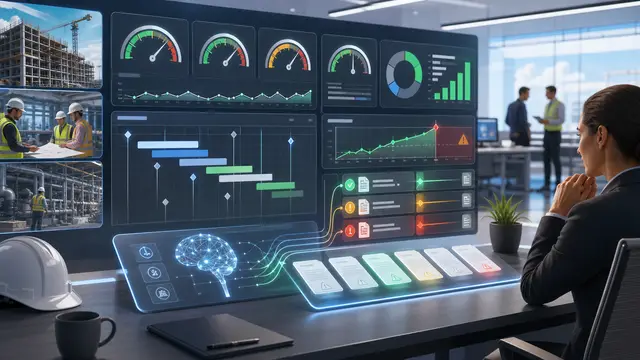
Next, connect the core systems. The automation should read job budgets, actual costs, commitments, labor entries, change orders, schedule status, and project notes. It does not need every possible field on day one. It needs enough information to explain why a variance is worth attention. For each exception, the system should create a short evidence pack that includes the job, cost code, budget, actuals, committed cost, variance amount, trend direction, related notes, and recommended owner.
The AI layer can help classify the likely cause. For example, it might identify the variance as labor productivity, material price change, unapproved scope, rework, subcontractor delay, billing timing, coding error, or missing documentation. Those labels should be treated as suggestions. The owner should confirm or correct them, and that feedback should improve future routing.
A useful review queue might include:
- New exceptions created since the last review.
- Exceptions that are growing.
- Exceptions waiting on owner response.
- Exceptions tied to unbilled change work.
- Exceptions where the explanation conflicts with the financial data.
- Jobs with multiple small variances that add up to material risk.
The workflow should end with a decision, not just an alert. Possible outcomes include submit change order, correct coding, approve planned overrun, rebalance staffing, escalate client issue, update forecast, or close as timing difference. Each decision should be logged with owner, date, rationale, and next follow-up. That creates a management record that is useful for both current control and future estimating.
Start with active jobs above a meaningful revenue threshold. Review the queue twice a week for a month. Compare the exceptions to month-end results. If the workflow surfaces real risk early, expand it. If it creates noise, adjust thresholds and labels before adding more complexity.
One practical design choice is to separate controllable variance from timing variance. A material invoice may hit before revenue is recognized. Labor may look high because a crew completed work ahead of schedule. A subcontractor commitment may appear risky until a pending change order is approved. If the automation treats every unfavorable number as a problem, managers will ignore it. The review queue should ask whether the variance is timing, coding, scope, productivity, price, quality, or schedule related. That distinction turns a warning into a decision.
The workflow should also recognize compounding risk. A single variance may be small, but a job with labor overrun, delayed change approval, and repeated field notes about access issues deserves attention. AI can summarize those related signals in plain language so the project manager does not have to open five systems before the review meeting. The most useful alert is not merely that cost is high. It explains why the pattern is worth a conversation now.
The operating cadence matters. Daily alerts may be appropriate for large active jobs, while weekly review may be enough for smaller projects. Finance should not own every exception. Some belong to project managers, some to procurement, some to billing, and some to operations leadership. Clear ownership prevents the queue from becoming another report that everyone reads and no one acts on.
There is also a learning loop. After each job closes, compare the variance alerts with final margin. Which alerts predicted real margin loss? Which were noise? Which cost codes repeatedly caused drift? Which managers corrected issues quickly? This review turns the automation into an estimating and process improvement tool. The company can update budgets, standard work, vendor expectations, and approval rules based on evidence gathered during active jobs.
The review design should include tolerance by job phase. Early-stage variance can be normal because setup costs arrive before progress is visible. Late-stage variance can be more dangerous because there is less remaining work to recover margin. The same dollar variance may deserve different treatment depending on percent complete, billing status, and remaining contingency. AI can summarize that context, but the thresholds should be set by finance and operations together.
Documentation discipline is another payoff. When the workflow asks for a reason code and next action, it creates a reusable body of project knowledge. Estimators can see where budgets were consistently thin. Operations leaders can see which vendors or work types create preventable overruns. Finance can see which variances were true cost problems and which were timing or coding issues. The automation becomes more valuable when it feeds learning back into planning, not just alerts into the current job.
Before scaling this workflow, document the baseline. Capture current cycle time, rework, escalation volume, missed commitments, and the decisions managers wish they had seen earlier. Then pilot the automation with a small group, review exceptions weekly, and tune the rules based on evidence. The strongest results usually come from a narrow workflow that teams trust, not a broad launch that produces more alerts than decisions.
Business Takeaway
Margin protection is not a month-end activity. It is a daily and weekly operating discipline. AI-assisted job cost variance review gives teams a way to see drift while it is still manageable, connect the numbers to the field reality, and route decisions before small issues become expensive lessons.
The best automation does not bury project managers in dashboards. It gives them a focused list of variances, the evidence behind each one, and a clear action path. That is how finance and operations move from explaining margin loss to preventing it.