What Happened
Recurring revenue depends on a quiet promise: when the next billing date arrives, the customer is ready, the payment method works, the invoice is understood, and the business can collect without drama. That promise often breaks in small ways before anyone sees a major problem. A card expires. A bank account changes. A customer contact leaves. A purchasing policy requires a fresh authorization. A billing portal password is lost. A payment retry fails while the account team assumes everything is fine.
These issues rarely look strategic at first. They show up as failed charges, delayed renewals, support tickets, collections emails, customer confusion, or manual adjustments in accounting. The company may still collect the money eventually, but the work becomes more expensive than it needed to be. Finance chases payment. Support answers questions that could have been prevented. Customer success tries to protect the relationship. Sales worries about the renewal. Leadership sees recurring revenue that looks solid in the forecast but behaves unpredictably in cash.
AI and automation can help by turning payment readiness into a managed workflow instead of a reactive cleanup exercise. The goal is not to let a model make financial decisions or pressure customers with careless messages. The goal is to watch the signals that usually appear before a failed payment, organize them into a useful review queue, and route the right next action before revenue is interrupted.
Most businesses already have the evidence. Billing platforms know upcoming invoice dates and failed payment codes. CRM systems know account owners and renewal timing. Support tools know whether customers are struggling with the portal. Email and chat records may show that a billing contact changed roles. Payment processors can identify expiring cards, authorization failures, and retry status. The problem is that these signals live in separate places and are reviewed at different speeds.
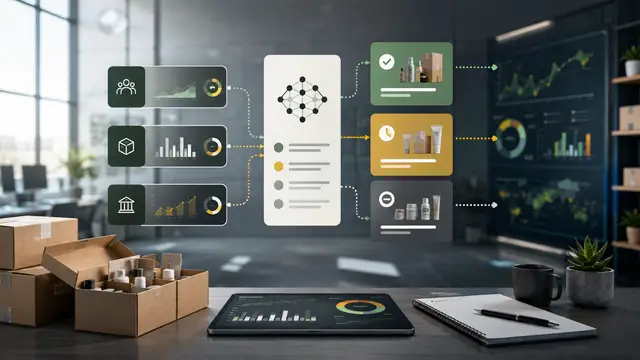
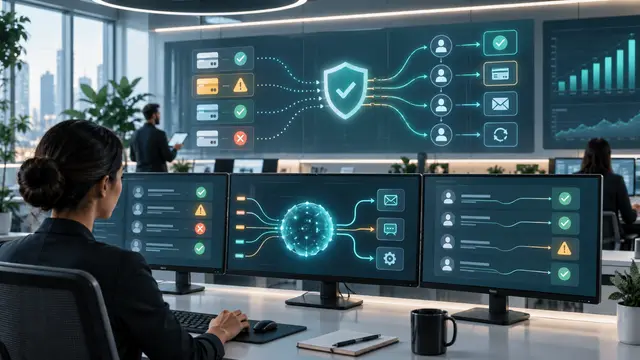
A practical payment method readiness workflow connects those signals into one operating routine. Before a recurring billing event, automation can identify accounts with expiring cards, recent failed payment attempts, missing billing contacts, upcoming renewal dates, open invoice questions, payment method changes, high account value, or recent service issues. AI can summarize the likely risk, explain what evidence supports it, and suggest the next lane for human review.
That distinction matters. A low-value account with an expiring card and a working self-service portal may need a simple reminder. A strategic customer with a failed bank authorization, an open support escalation, and a contract renewal next month needs a coordinated account action. A customer who already updated payment details but still appears in a failed-payment list needs data reconciliation, not more outreach. AI becomes useful when it helps the business tell those situations apart.
The best workflows also recognize timing. A payment problem discovered on the due date creates urgency and fewer options. The same problem discovered thirty days earlier can be handled with a friendly reminder, a billing contact confirmation, a portal access check, or an account-owner task. Readiness is about giving the business more time to act with context and less pressure.
This topic is especially important for subscription businesses, service contracts, membership programs, managed service providers, ecommerce subscriptions, maintenance plans, software companies, and any organization that depends on repeat billing. Even companies that do not describe themselves as subscription businesses may have recurring invoices, retainers, installment plans, warranty renewals, or automated payment arrangements. When payment readiness is weak, the effect can spread through cash flow, customer experience, support workload, and renewal confidence.
The workflow should stay grounded in customer trust. A failed payment is not always a bad customer. It may be an expired card, a fraud-prevention hold, a changed approval process, a bank transition, a missing purchase order, or a simple confusion about the invoice. Treating every case as delinquency can damage the relationship. Treating every case as harmless can damage cash. AI can help classify the context, but the business must define the tone, timing, escalation rules, and review points.
Why It Matters for Businesses
Payment readiness matters because recurring revenue is only valuable when it turns into dependable cash. A dashboard may show active contracts, active subscribers, or scheduled invoices, but those numbers can hide operational friction. If a portion of recurring revenue routinely requires manual rescue, the company is carrying a cost that may not be visible in the headline revenue number.
The first impact is cash predictability. Failed payments create timing gaps. Finance may need to revise short-term cash expectations, collections teams may spend time on preventable outreach, and managers may have less confidence in the relationship between billed revenue and collected cash. A readiness workflow improves the signal before the cash gap appears.
The second impact is labor. Every failed payment creates small tasks across teams. Someone checks the processor response. Someone looks for the billing contact. Someone sends a reminder. Someone answers the customer question. Someone updates the CRM. Someone decides whether service should continue, pause, or be escalated. One case may be minor. Hundreds of cases become a recurring operating expense.
The third impact is customer experience. Customers do not always understand why payment failed. They may be embarrassed, annoyed, or surprised. They may think the business should have notified the right person earlier. They may be frustrated if service is interrupted because an administrative detail was missed. A controlled workflow lets the business communicate sooner, more clearly, and with the right context.
The fourth impact is retention. Payment friction can look like churn risk even when the customer wants to stay. If a customer loses access, receives repeated failed-payment notices, or has to explain billing details multiple times, the renewal conversation starts from irritation. For customer success teams, payment readiness is part of relationship health, not just finance administration.
The fifth impact is data quality. Payment failures often expose weak account records. The billing contact is outdated. The legal entity name changed. The portal user does not match the approver. The payment method belongs to a department that no longer owns the relationship. The company may fix the immediate charge but leave the underlying record broken. AI can help identify those recurring causes so the business improves the source process.
The sixth impact is governance. Payment data is sensitive, and automated workflows must be designed carefully. A readiness process should not expose full payment details to people who do not need them. It should not store unnecessary card or bank information in prompts, tickets, or notes. It should use approved processor signals, masked identifiers, customer account metadata, and secure links rather than copying sensitive data into open systems.
For leaders, the value is measurable. A payment readiness workflow can track:
- Failed-payment rate by customer segment and billing type
- Recovery time after a failed charge
- Percentage of expiring payment methods resolved before invoice date
- Number of customer contacts corrected before billing
- Manual collection touches avoided
- Recurring revenue protected from avoidable interruption
- Customer support tickets tied to payment confusion
- Accounts where payment friction preceded churn or downgrade risk
These measures help the business avoid vague automation claims. The point is not to say that AI is saving time in general. The point is to show whether fewer payments fail, whether failures recover faster, whether customers receive clearer communication, and whether teams spend less effort chasing preventable exceptions.
Payment readiness also creates better management conversations. Instead of asking why collections is busy, leadership can see which causes are driving work. Are expired cards concentrated in one customer segment? Are ACH failures tied to missing authorization updates? Are high-value accounts missing billing contacts? Are portal issues causing avoidable support tickets? Are retries happening without account-owner visibility? Once the causes are visible, the business can improve the process rather than repeatedly treating symptoms.
This is where AI provides leverage. It can read messy context, compare signals, classify cases, and summarize next steps. It can say that a failed payment appears connected to an expired card and an inactive billing contact. It can note that the account has a renewal in forty-five days and an open support case. It can recommend customer-success review before sending a standard dunning message. That kind of context helps people make better decisions faster.
The Practical Automation Opportunity
The practical opportunity is to build a payment readiness queue that runs before the billing date, not only after a failure. Start with a narrow segment where the value is easy to see. Good pilots include high-value recurring accounts, customers renewing in the next ninety days, subscriptions with annual prepayment, accounts with prior failed payments, or payment methods expiring within sixty days.
Define the trigger events first. A readiness workflow can activate when a payment method is near expiration, a recurring invoice is scheduled, a payment retry fails, a billing contact changes, a customer opens a payment-related support ticket, a renewal approaches, or a payment method is removed without replacement. Each trigger should create a case with an owner, due date, reason code, confidence level, and evidence summary.
Next, define the data sources. The first version does not need every system in the company. It may need the billing platform, payment processor status, CRM account owner, renewal date, support ticket tags, and customer communication preferences. If those sources are enough to make better decisions, start there. Add more sources only after the team trusts the first queue.
AI can support the workflow in several focused ways:
- Summarize the risk in plain language
- Classify the reason as expiring method, failed authorization, missing contact, portal issue, invoice confusion, processor retry, or account review
- Compare the billing contact in CRM with the payment contact in the billing platform
- Identify whether the account has recent support or renewal activity
- Draft internal tasks for finance, customer success, or account management
- Suggest customer-facing language that matches the account situation
- Detect repeated failure patterns that point to a process issue
The workflow should separate customer communication from internal decision support. AI can draft a message, but the business should define which messages can be sent automatically and which require review. A routine expiring-card reminder may be safe to automate if it uses approved language and secure portal links. A high-value account with open service issues should probably route to the account owner first.
Build exception lanes. Not every case belongs to finance. Some cases belong to customer success because payment friction may affect retention. Some belong to support because the customer cannot access the portal. Some belong to sales operations because the billing account is connected to a renewal or expansion. Some belong to data stewardship because the account record is wrong. Clear lanes keep the queue from becoming another shared inbox.
Use confidence levels. A system may know with high confidence that a card expires before the next invoice. It may have lower confidence that a billing contact is inactive based on bounced email or job-title changes. It may only suspect that payment failure is connected to a customer dispute. The workflow should show that confidence instead of presenting every recommendation with the same certainty.
Protect sensitive information. The workflow should not expose full card numbers, bank details, security codes, or unnecessary personal data. Use masked identifiers, payment processor statuses, account IDs, and secure links to approved systems. Keep audit records focused on actions and outcomes, not raw payment data. Involve finance, security, and compliance owners before expanding automation around payment information.
Create a human override path. Sometimes a customer should receive extra time because of relationship context, contract terms, service issues, or executive agreement. Sometimes service should continue while the payment method is corrected. Sometimes an account should be paused quickly. The workflow should record the decision, the owner, and the reason. That documentation protects consistency and reduces second-guessing later.
Design the customer message carefully. Payment reminders should be useful, specific, and calm. They should explain what needs attention, identify the secure path to update information, and avoid unnecessary pressure. They should also avoid exposing sensitive payment details in email. If the business serves larger accounts, messages may need to go through the account owner rather than directly to the end user.
Measure the first ninety days. Compare failed-payment rate, recovery time, support tickets, manual touches, and protected recurring revenue against the prior baseline. Also review sample cases. Did the workflow route the right owner? Was the summary accurate? Were customers contacted at the right time? Did the process catch problems before billing? Did it create noise? Those reviews help tune the rules.
The most valuable insights may come from patterns. If many cases are caused by missing billing contacts, the business should improve customer onboarding. If many failures happen after bank changes, the business may need better authorization renewal steps. If portal confusion creates repeated support tickets, the portal experience needs attention. If retries happen without human visibility, finance may need clearer escalation thresholds.
A mature payment readiness workflow can become part of a broader revenue operations control system. It can connect with renewal readiness, invoice clarity, account health, customer communication, and cash forecasting. But the first version should stay simple: find the accounts most likely to experience avoidable payment friction, prepare the context, route the owner, and record the result.
Business Takeaway
Recurring revenue should not depend on last-minute payment rescue. Failed charges, expired payment methods, missing billing contacts, and confused customers are operational signals that can be handled earlier when the business has the right workflow. AI makes those signals easier to interpret. Automation makes the follow-through consistent. People still own the judgment, relationship, and policy decisions.
For LJ Web Management clients and similar business teams, the best next step is to pilot payment readiness on one recurring revenue segment. Choose the trigger, define the evidence, assign owner lanes, protect sensitive data, and measure whether fewer payments fail or recover late. When the workflow can prove faster recovery, fewer manual touches, better customer communication, and more dependable cash, it becomes more than a billing tool. It becomes a practical operating rhythm for protecting revenue before friction reaches the customer.