What Happened
Service-level credits often become difficult because the review starts too late. A customer reports that a commitment was missed. Support checks the ticket history. Operations reviews the timeline. Finance looks at contract language. Account management weighs the relationship. By the time everyone has an opinion, the customer may already feel that the business is debating responsibility instead of solving the problem. An AI-assisted SLA credit review workflow can prepare the evidence and decision path before the issue becomes a finance dispute.
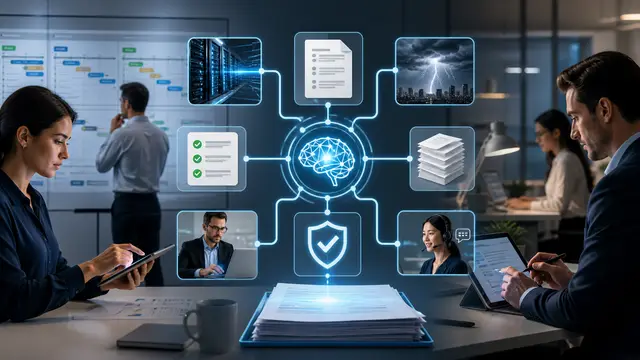
The workflow begins with a simple idea: every potential service credit should be treated as a structured case. The case needs the customer account, contract or service plan, relevant commitment, event timeline, actual performance, exclusions, prior communications, proposed remedy, approval owner, and customer-facing explanation. AI can help gather and summarize that information from tickets, monitoring logs, CRM notes, contract excerpts, billing records, and service reports.
This does not mean AI should decide whether a credit is owed. Credits involve policy, relationship judgment, contract interpretation, and financial impact. The AI layer should prepare the review packet, identify gaps, classify the case, and draft options. People decide. Automation makes sure they are deciding from the same fact pattern and that the decision is recorded clearly.
Businesses that sell managed services, software subscriptions, maintenance plans, delivery commitments, support tiers, or response-time guarantees can benefit from this approach. Even when credits are rare, the process around them matters. A confusing credit review can damage trust more than the original service miss.
Without structure, the review often turns into a relay. Support asks operations for dates. Operations asks finance what the contract says. Finance asks account management whether the relationship is sensitive. Account management asks support what was promised. Each handoff adds delay. AI can turn that relay into a prepared case that moves through the right reviewers in order.
Why It Matters for Businesses
The immediate business value is consistency. Customers notice when similar issues receive different treatment. Internal teams notice when decisions depend on who happens to be available. AI-assisted review can apply the same intake questions, evidence standards, thresholds, and routing rules across cases. That does not eliminate judgment. It makes judgment more defensible.
Finance benefits because credit requests arrive with cleaner evidence. Instead of receiving a vague request to adjust an invoice, finance receives a case that explains the commitment, the measured miss, the approved remedy, and the account context. That reduces back-and-forth and lowers the chance that billing adjustments are made without enough documentation.
Account managers benefit because they can communicate sooner. A customer waiting for an answer does not need an instant final decision in every case, but they do need to know the company is handling the issue deliberately. AI can draft a factual status update that avoids overpromising while explaining what is being reviewed. That protects the relationship while the company completes the approval path.
Leadership gains better visibility into whether SLA misses are isolated, systemic, or caused by unclear contracts. If cases are structured, leaders can see patterns by service line, customer segment, region, vendor dependency, support queue, or product area. Credits then become a signal for operational improvement, not just a financial concession.
The workflow also supports better contract hygiene. Repeated ambiguity in credit reviews may reveal that service commitments are written in language that teams cannot measure cleanly. That is not just a billing problem. It is a product and sales enablement problem. Structured cases give leaders evidence to refine future terms and customer expectations.
The Practical Automation Opportunity
The automation should detect potential SLA credit cases from support tickets, incident records, customer emails, account notes, monitoring alerts, or billing disputes. Trigger language might include missed response time, downtime, late delivery, service credit, outage, missed appointment, guarantee, or invoice adjustment. The workflow should not assume every trigger is valid. It should create a review case and gather evidence.
The AI layer should build a timeline. What was promised? When did the clock start? What happened next? Were there pauses, customer delays, exclusions, planned maintenance windows, dependency failures, or prior exceptions? Which records support each event? A timeline is far more useful than a long collection of screenshots. It lets reviewers see the issue quickly and identify gaps.
Approval routing should reflect both dollar impact and relationship sensitivity. A small credit on a routine account may need one approval. A large credit, strategic customer, repeated issue, or ambiguous contract term may need account leadership, operations, and finance. The workflow should also preserve the reasoning behind the decision so future cases can be compared with prior decisions.
Measurement should include credit review cycle time, disputed invoice aging, repeat SLA credit requests, root causes by category, customer satisfaction after resolution, and credits as a percentage of recurring revenue or service revenue. The goal is not to deny more credits. The goal is to handle valid credits faster, challenge weak requests with evidence, and fix the upstream causes that create avoidable claims.
A pilot can begin with one service plan and one credit type. Build the timeline builder, contract excerpt lookup, reviewer summary, and approval log. Keep final decisions with the responsible managers. Once the process shortens review time and reduces billing confusion, expand to additional commitments and higher-volume service lines.
The workflow should begin by translating contract language into operational checkpoints. A commitment that says response within four business hours needs a clear start event, stop event, business-hours calendar, exclusion rules, and source system. A commitment that says availability needs monitoring records and maintenance windows. A commitment that says delivery by a certain date needs fulfillment and carrier context. AI can help map the language, but business owners must approve how each commitment is measured.
Case quality depends on evidence ranking. Not every record has equal weight. A customer email, system alert, technician note, monitoring log, and billing comment may tell different parts of the story. The workflow should show source, timestamp, owner, and confidence. It should identify conflicts rather than smoothing them over. Reviewers need to know where the case is strong and where judgment is required.
Customer communication should be separated from internal review notes. Internally, the team may discuss ambiguity, precedent, cost exposure, or operational weakness. Externally, the customer should receive a clear and professional explanation. AI can draft both, but the workflow should keep them distinct. That reduces the risk of sending internal speculation to the customer while still helping the company make a thoughtful decision.
Precedent management is another important feature. If the business approved a credit in a similar situation last quarter, reviewers should be able to see that context. Precedent does not mean the same decision is always required. It means decision makers understand how current judgment compares with prior treatment. This is especially useful for strategic accounts, recurring incidents, and ambiguous contract terms.
The review should close with root-cause ownership. A valid credit may point to a monitoring gap, staffing constraint, vendor dependency, onboarding mistake, unclear promise, or service design problem. If the workflow only issues the credit, the same condition will return. Connecting the credit case to prevention work turns a finance adjustment into an operating signal.
Operational ownership should be explicit from the start. A potential credit case may begin in support, but the responsible facts may live with infrastructure, field service, implementation, customer success, or a vendor manager. The workflow should identify which team controls the next evidence step and which leader owns the final recommendation. This prevents cases from drifting between departments while the customer waits.
AI can help reviewers separate entitlement from goodwill. A customer may not be contractually owed a credit, but the relationship context may justify a courtesy adjustment or service recovery action. The workflow should label those paths differently. Contractual credit, goodwill credit, operational make-good, service extension, and no-credit decision each require different documentation and communication. Mixing them together creates confusion for finance and inconsistent expectations for customers.
The workflow should also include customer history. A first-time issue for a long-standing account may deserve a different conversation than a repeated claim on an account with chronic configuration problems. AI can summarize prior incidents, previous credits, open risks, and account notes so managers can make a complete decision. The summary should avoid emotional labels and focus on verified history.
For finance teams, the closeout step matters. Once a decision is approved, the workflow should create the adjustment request with amount, reason code, tax or billing implications, approval record, and customer communication status. If the request is denied, it should record the reason and approved explanation. This creates cleaner audit trails and reduces the chance of unresolved disputes appearing again during collection.
Controls should be reviewed after several cases. If the AI regularly marks cases as unclear, the measurement rules may need better source data. If many cases require senior approval, thresholds may be too low or service commitments may be too ambiguous. The automation should make these design issues visible so leaders can improve the service model, not just process credits faster.
Business Takeaway
An AI SLA credit workflow turns a sensitive customer issue into a disciplined review process. It gathers evidence, creates a timeline, routes the decision, and helps teams communicate clearly. That protects finance from unsupported adjustments and protects customers from vague, slow responses when service commitments are questioned.