What Happened
Cash application is one of those finance processes that appears simple from a distance. A payment arrives, a remittance detail identifies the invoices, and the receivable is cleared. In practice, the work is full of exceptions: abbreviated customer names, partial payments, combined invoices, deductions, bank descriptions that omit useful identifiers, and remittance advice delivered through several inboxes. Teams often respond by asking experienced staff to search systems, inspect documents, and make judgment calls. That keeps cash moving, but it also creates a quiet operating dependency on individual memory.
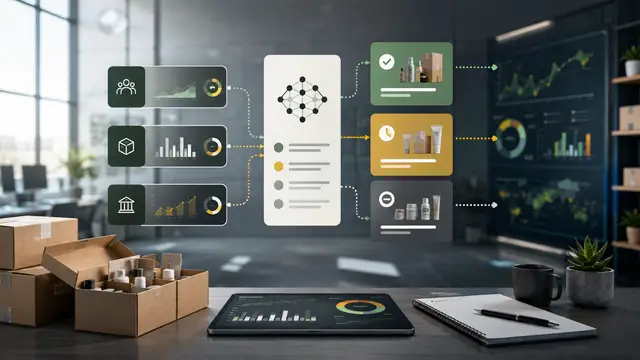
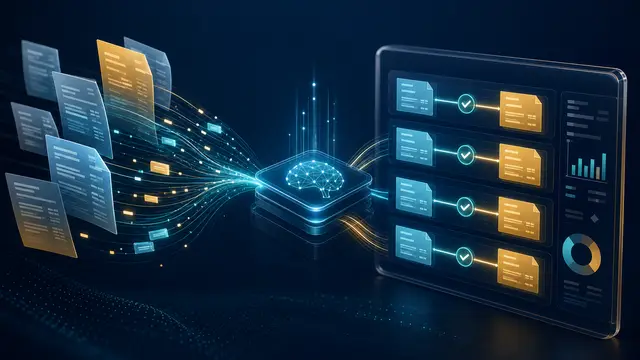
AI-assisted remittance matching changes the shape of that work. It can read the incoming evidence, extract amounts and references, normalize customer identities, compare possibilities across open receivables, and assign a confidence level to each proposed match. Automation then routes only the uncertain cases to an analyst. The goal is not to let software post money without control. The goal is to give people a focused work queue, with a visible explanation of why a proposed match is likely correct.
A useful implementation begins with a narrow slice of the process. A business can start with remittances received by email, for example, and map the most common document formats. The workflow can create a structured record for every payment, retain the source file, propose invoice matches, and distinguish between high-confidence straight-through items and exception items. That division is more valuable than a generic promise of automation because it exposes the true source of delay: missing evidence, not merely too few keystrokes.
Why It Matters for Businesses
The business consequence reaches beyond accounting speed. When cash is unapplied, finance leaders have a weaker view of collections, sales teams may contact customers who have already paid, and customer service representatives can spend time resolving avoidable confusion. A reliable matching workflow creates a shared operational record. Everyone can see whether a payment is matched, waiting for remittance, held for a deduction review, or escalated for customer outreach.
Control matters as much as throughput. Finance teams should retain approval rules for write-offs, deductions, and unusually large allocations. A good workflow records the evidence used, the model's confidence, the reviewer decision, and the final posting. That audit trail is what turns an AI suggestion into a defensible financial process. It also creates feedback: recurring exceptions can reveal a customer billing issue, an unclear payment instruction, or a sales process that needs tighter terms.
The right success measures are practical. Track the share of payments applied within a defined service window, exception age, analyst touches per payment, unapplied-cash balance, and the reversal rate for automated suggestions. These measures connect automation quality to working-capital visibility rather than treating the technology as a standalone experiment.
The Practical Automation Opportunity
Start by defining a small matching policy. Agree on which identifiers are strong enough for automatic proposals, which amount tolerances are acceptable, and which situations always require review. Connect the bank feed, receivables system, remittance inbox, and document store so the workflow has a complete evidence chain.
Build an exception queue that tells an analyst what to do next. Each item should show the payment, likely customer, candidate invoices, the evidence behind the recommendation, and the missing detail if confidence is low. Give the reviewer a short choice set: accept, split, request remittance, assign to deduction review, or hold. Those decisions should improve the matching rules over time.
Pilot with one payment channel and a defined customer group. Review every automated recommendation during the first period, then expand the threshold for straight-through processing only after the reversal rate and evidence quality are understood. This sequencing protects the ledger while making the gain visible quickly.
Implementation should start with a decision inventory. List every decision the current team makes, the evidence it uses, the role that owns the final decision, and the downstream system affected. That exercise prevents a common automation mistake: encoding an informal shortcut as though it were policy. It also reveals where exceptions cluster. A rule that has ten different informal exceptions is usually not ready to be automated without a clearer business definition.
Data stewardship deserves explicit ownership. The workflow needs named owners for source fields, reference data, business rules, model prompts, and approval thresholds. When a field changes meaning or a source system is replaced, someone should assess the downstream effect before the automation quietly produces misleading work. A monthly operating review can examine data quality, overdue items, overrides, and feedback from the people using the queue.
Design the human handoff as carefully as the automated step. A reviewer should receive a concise brief, direct access to source evidence, a short set of allowed actions, and a clear escalation route. The reviewer should not need to reconstruct the case from multiple inboxes. At the same time, the system should not hide uncertainty. Low-confidence recommendations and missing evidence should be visible, because they are often the most valuable work for an experienced employee.
A phased rollout reduces risk. Begin with observation mode, where the workflow creates recommendations but does not change a record. Compare its output with experienced staff decisions and record the reason for every material difference. Next, allow policy-approved actions for high-confidence, low-risk cases while retaining review for exceptions. Only after stable results should the business expand the population, source systems, or decision scope.
Build a practical measurement baseline before launch. Capture current turnaround time, rework, backlog age, escalation volume, and the effort spent requesting missing information. After rollout, compare the same measures by work type, not just as one blended average. A faster process that creates more reversals, customer confusion, or control failures is not a successful process. The intended result is reliable capacity: less time spent finding and formatting information, and more time spent deciding and improving.
Communicate the operating model to the people affected by it. Explain what the workflow will do, what it will never do without approval, how to correct a recommendation, and where feedback goes. Adoption improves when employees see that automation removes repetitive gathering work while preserving their authority over business exceptions. It also produces better feedback, which is necessary to keep the workflow accurate as policies and customer behavior change.
Finally, keep the workflow reviewable. Maintain a record of source inputs, generated recommendations, user decisions, timestamps, and rule versions. Periodically sample completed cases, including cases that the system marked as routine. This audit habit supports governance and gives the business a way to find process improvement opportunities that would be invisible in a purely manual operation.
Consider integration failure as an operating condition, not an edge case. A source system may be unavailable, an attachment may arrive late, or a required identifier may be malformed. The workflow should show a clear status, preserve what was received, avoid duplicate actions on retry, and route the case to a recoverable exception path. A well-designed recovery path protects both customer experience and employee confidence.
Decision thresholds should be reviewed against the cost of being wrong. In some workflows, a false positive creates little harm and can be corrected easily. In others, a mistaken action can affect a customer, a ledger, a compliance obligation, or a security boundary. Match automation scope to that risk. Require stronger evidence and human approval where the impact is high, and use routine low-risk actions to build confidence gradually.
The workflow also needs a practical change-management cadence. Business policies, supplier practices, product offerings, and staffing patterns change. Set a recurring time to review whether the original assumptions still hold, whether new exceptions should become standard paths, and whether old rules can be retired. This keeps the automation aligned with actual operations rather than preserving a snapshot of how work used to happen.
At leadership level, report outcomes alongside limitations. Share where automation reduced cycle time or prevented rework, but also share the exceptions that remain manual and why. That transparency helps the business direct improvement investment to the right place. It reinforces the central principle: automation should make responsibility clearer, evidence easier to use, and service more dependable.
Before expanding the workflow, test its behavior with representative edge cases. Include incomplete records, contradictory source values, unusual amounts or dates, cases that cross ownership boundaries, and situations that require an exception approval. Ask the people who do the work to review the outcomes. Their experience will identify ambiguity that is invisible in a process diagram and will improve both the instructions and the data model.
Keep automation messages useful. A reminder should identify the item, the required next step, the deadline, and a direct route to act. An escalation should explain what has already been attempted and why the item needs attention. Avoid sending broad status messages that force recipients to search for context. Good notification design is a material part of operational productivity.
As the workflow matures, look for upstream prevention. Repeated exceptions are rarely only a queue-management problem. They may be caused by a confusing customer instruction, an incomplete form, a missing validation, or a policy that is difficult to apply. Use exception data to improve the originating process, then verify that the change actually reduces the recurring issue.
Document the benefit in business language. Employees, leaders, and customers should be able to see whether the new process creates a more dependable response, clearer accountability, fewer avoidable delays, or better quality decisions. That shared understanding makes the automation sustainable and gives the organization a disciplined way to choose the next workflow worth improving.
Business Takeaway
AI-assisted remittance matching is a cash-visibility workflow, not a replacement for financial judgment. Put automation around evidence capture and candidate matching, reserve decisions for controlled exceptions, and measure the reduction in unapplied cash and analyst effort. The most durable result is a process that gets faster while becoming easier to explain.